
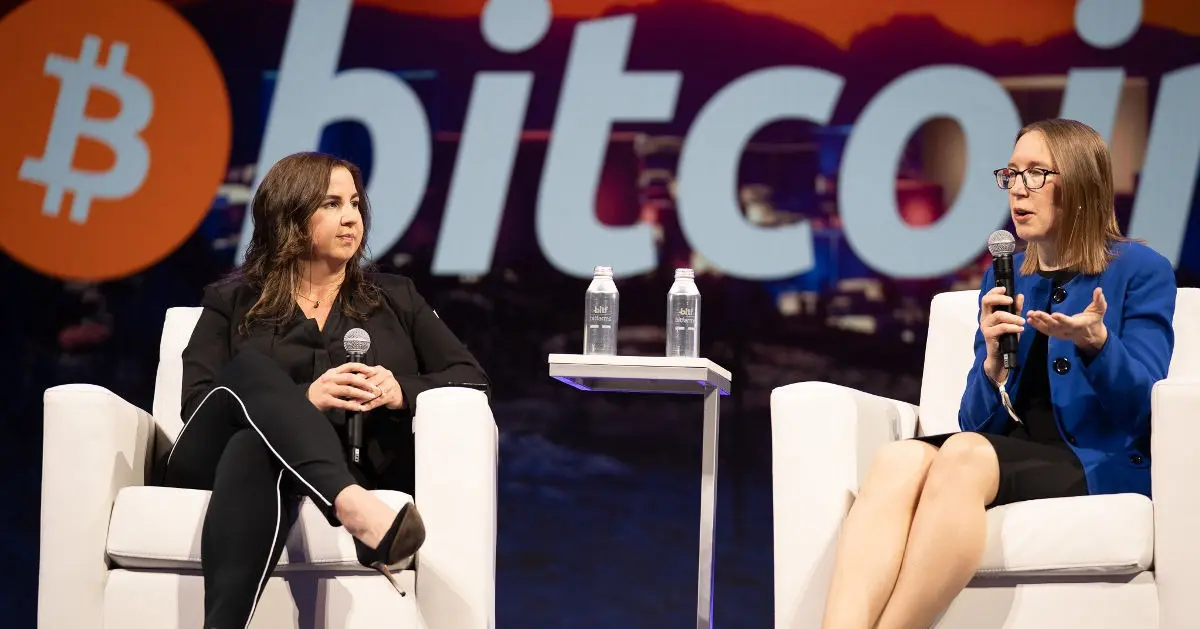
NEW YORK — Outgoing Securities and Exchange Commission Commissioner Hester Peirce has issued a direct challenge to the regulatory establishment, calling on government watchdog agencies to fundamentally rethink how they monitor the nation’s financial system. Speaking at the Securities Industry and Financial Markets Association (SIFMA) Digital Assets Conference in New York on Wednesday, Peirce urged regulators to press for significantly less personal data collection rather than continuously expanding federal oversight into the private lives of market participants.
In a keynote address focusing on digital identity systems, privacy-preserving technology, and decentralized financial networks, Peirce targeted the expansive landscape of modern financial regulation. She directed specific criticism toward traditional Know Your Customer (KYC) and Anti-Money Laundering (AML) mandates, arguing that the existing supervisory framework has become overly intrusive, increasingly inefficient, and fundamentally misaligned with the constitutional and privacy values of a free society.
Her remarks come at a critical turning point for the agency and the broader digital asset landscape. United States regulators are currently racing ahead with crypto rulemaking to establish long-awaited guidelines for the fast-moving sector. Meanwhile, Peirce, who earned the widely recognized nickname “crypto mom” among market participants for her consistently approachable and constructive regulatory stance toward the digital asset ecosystem, is set to step down from her post at the commission in November.
Reflecting on the evolution of regulatory surveillance and the emerging capabilities of modern financial technology, Peirce cautioned that policy choices made today will permanently shape the relationship between citizens, financial institutions, and the state.
Addressing the audience of industry executives, legal experts, and fellow regulators in New York, Peirce framed the current environment as a decisive historical junction for regulators and the public alike. She emphasized that society sits at a pivotal crossroads regarding how financial data is handled and monitored by authorities.
Outlining the choices ahead, Peirce argued that down one path lies the status quo, characterized by ever-increasing data collection, expanding intermediary surveillance, and progressively restrictive Know Your Customer requirements. She warned that continuing down this established trajectory threatens to transform the core infrastructure of the American financial system into a pervasive regulatory panopticon where every transaction and identity detail is continuously logged, analyzed, and scrutinized by third parties and government agencies.
Conversely, Peirce presented an alternative vision for the future of financial regulation—one that leverages advanced technological developments to achieve public policy goals without sacrificing personal liberty. Down the second path, she explained, lies a distinct opportunity to deploy modern cryptographic systems and digital identity structures to enhance law enforcement’s ability to detect and apprehend actual criminals, while simultaneously collecting far less sensitive personal information than ever before. She stressed that by monitoring market activities more sparingly and intentionally, regulators can fulfill their statutory duties while honoring and protecting the constitutional privacy rights of ordinary Americans.
A central theme of Peirce’s address was a critique of the fundamental logic underpinning traditional anti-money laundering frameworks. She directly challenged the long-held regulatory assumption that accumulating vast mountains of personal information on millions of law-abiding citizens is an effective or necessary method for uncovering financial crime.
In her view, forcing financial institutions to continuously expand their customer data troves creates counterproductive friction for legitimate economic activity while failing to improve security outcomes. Peirce argued that building ever-larger haystacks of consumer data actually makes finding the needle—the specific instances of bad actors and illicit transactions—significantly harder for law enforcement agencies. Rather than clarifying potential criminal activity, the overwhelming volume of non-criminal data dilutes focus and strains investigative resources.
Furthermore, Peirce pointed out the severe cybersecurity and systemic risks inherent in accumulating huge volumes of sensitive identity records across the financial sector. She noted that every single stored data point represents an operational liability, raising the immediate risk of catastrophic data breaches, unauthorized leaks, identity theft, and corporate or governmental misuse. Centralized repositories of highly sensitive identity information naturally become attractive targets for malicious hackers and foreign adversaries, ultimately undermining systemic security in the name of regulatory compliance.
Peirce also criticized what she identified as an entrenched institutional mindset among financial watchdogs—a bureaucratic impulse fixated on continuous data expansion. She characterized this mindset as a regulatory philosophy where officials operate under an unyielding "data go up" directive, constantly seeking to mandate broader reporting requirements and collect larger quantities of personal information. Drawing a sharp analogy to the digital asset market itself, Peirce compared this bureaucratic fixation on accumulating data to the speculative obsession with rising asset prices frequently exhibited by cryptocurrency traders who champion a "number go up" mentality.
To move away from this surveillance-heavy approach, Peirce highlighted advanced cryptographic innovations that she argued could allow financial markets to maintain compliance and security without compromising consumer privacy. Specifically, she pointed to emerging technological tools such as zero-knowledge proofs and attribute-based credentials as viable, privacy-preserving alternatives to traditional identification methods.
These cryptographic tools enable individuals to mathematically confirm crucial compliance facts—such as verifying a user’s legal age, confirming their status as an accredited investor, or proving their absence from government sanctions lists—without exposing, transmitting, or storing the underlying personal identity details. By using zero-knowledge architectures, a financial platform can verify that a user meets all legal and regulatory criteria to execute a trade or access a service without the firm ever taking possession of sensitive documents like government identification cards, social security numbers, or private addresses.
In addition to technological innovations, Peirce offered practical policy suggestions to immediately reduce the unnecessary duplication of sensitive customer information within the regulated financial industry. She urged the SEC and partner regulatory bodies to establish clear pathways that allow regulated financial firms to rely on identity verification checks that have already been conducted by other compliant, regulated institutions.
Under the current framework, every individual broker-dealer, exchange, or financial intermediary is typically forced to independently collect, verify, and retain redundant sets of sensitive identity documentation from the same client. Peirce argued that permitting inter-institutional reliance would significantly reduce the overall volume of personal data circulating throughout the financial system, lowering compliance costs for businesses while substantially shrinking the surface area vulnerable to data theft and security compromises.
Peirce’s remarks come amid significant political and regulatory shifts in Washington regarding the oversight of digital assets and traditional capital markets. Under the previous leadership during President Joe Biden’s administration, the SEC adopted an aggressive enforcement-first approach toward the crypto industry. Led by Biden-appointed former SEC Chair Gary Gensler, the agency frequently launched high-profile lawsuits and enforcement actions against major cryptocurrency platforms and firm executives, alleging widespread offerings of unregistered securities and asserting broad jurisdictional authority over digital assets.
However, the regulatory posture surrounding the digital asset industry has experienced a notable shift following Donald Trump’s return to the presidency. Since the presidential transition, federal regulatory agencies have signaled a far more friendly and accommodating stance toward watchdogging the digital asset space, prioritizing regulatory clarity and market integration over continuous litigation.
As part of this evolving regulatory landscape, Peirce was appointed to lead the SEC’s specialized Crypto Task Force in 2025, positioning her at the center of the commission’s effort to re-evaluate its approach to digital tokens, decentralized protocols, and digital identity standards.
Despite these administrative shifts, the broader effort to establish a comprehensive statutory framework for digital assets continues to face political hurdles in Washington. U.S. regulators are currently moving forward with federal rulemaking initiatives aimed at creating clear, enforceable guidelines for the fast-evolving digital asset sector, even after landmark cryptocurrency legislation, known as the Clarity Act, was blocked in Congress last week. The failure of the Clarity Act leaves administrative rulemakers like the SEC with the task of defining market boundaries and investor protections through administrative channels.
Throughout her tenure at the commission, Commissioner Peirce has carved out a unique position as one of the regulatory community’s most vocal defenders of individual autonomy and technological innovation. Despite her popular industry moniker of "crypto mom"—a nickname earned through her frequent formal dissents against SEC enforcement actions and her consistent advocacy for sensible innovation—Peirce has historically distanced herself from being categorized purely as an industry cheerleader. She has previously clarified that she would not describe herself as a simple advocate for the cryptocurrency industry, but rather as a "freedom maximalist" who is primarily motivated by a desire to preserve individual choice, personal privacy, and voluntary market interactions.
As Peirce prepares to conclude her service with the Securities and Exchange Commission in November, her address at the SIFMA conference underscores a fundamental vision for the future of financial oversight. By advocating for advanced cryptographic identity tools, reduced regulatory data collection, and a structural retreat from broad surveillance models, Peirce presented a case that financial integrity and personal privacy do not have to be mutually exclusive. As regulators continue to shape the rules governing digital assets and modern capital markets, her call to rebuild financial rails around privacy-preserving principles highlights an enduring debate over the balance between state surveillance, regulatory compliance, and individual liberty in the digital age.